What costs money in insurance is almost never the cover you bought. It is the exclusion you discover when the loss occurs, in a contract signed without being read. A broker's work consists largely of making that reading happen before the signature rather than after the damage.
An intermediary, not an insurer
The distinction is not about vocabulary. An insurer carries or manages the risk according to its actual role: it issues the contract, collects the premium, sets aside reserves and decides on claims. A broker is an intermediary: they search, compare, explain, accompany, and issue no contract in their own name.
That position has consequences a client is better off knowing at the first meeting. The broker cannot guarantee a payout, because the decision is not theirs. They cannot change a clause in a contract they do not draft. They can, on the other hand, refuse to put forward an offer they consider unsuitable, which a sales counter generally does not.
Nor is an intermediary automatically independent. Depending on the country and on their mandate, some distribute the products of a single company, others approach several insurers, others again operate under a different status. Legal definitions, conditions of practice and job titles vary from one state to another: there is no universal status of broker, and the only way to know who you are talking to is to ask.
Gathering the facts: describing a risk before looking for a contract
An engagement does not start with an offer, it starts with a description. What is to be covered, for whom, for how long, under what conditions of use. A vehicle, a home, a journey, a business activity, a workforce: each is described through verifiable facts rather than through a category.
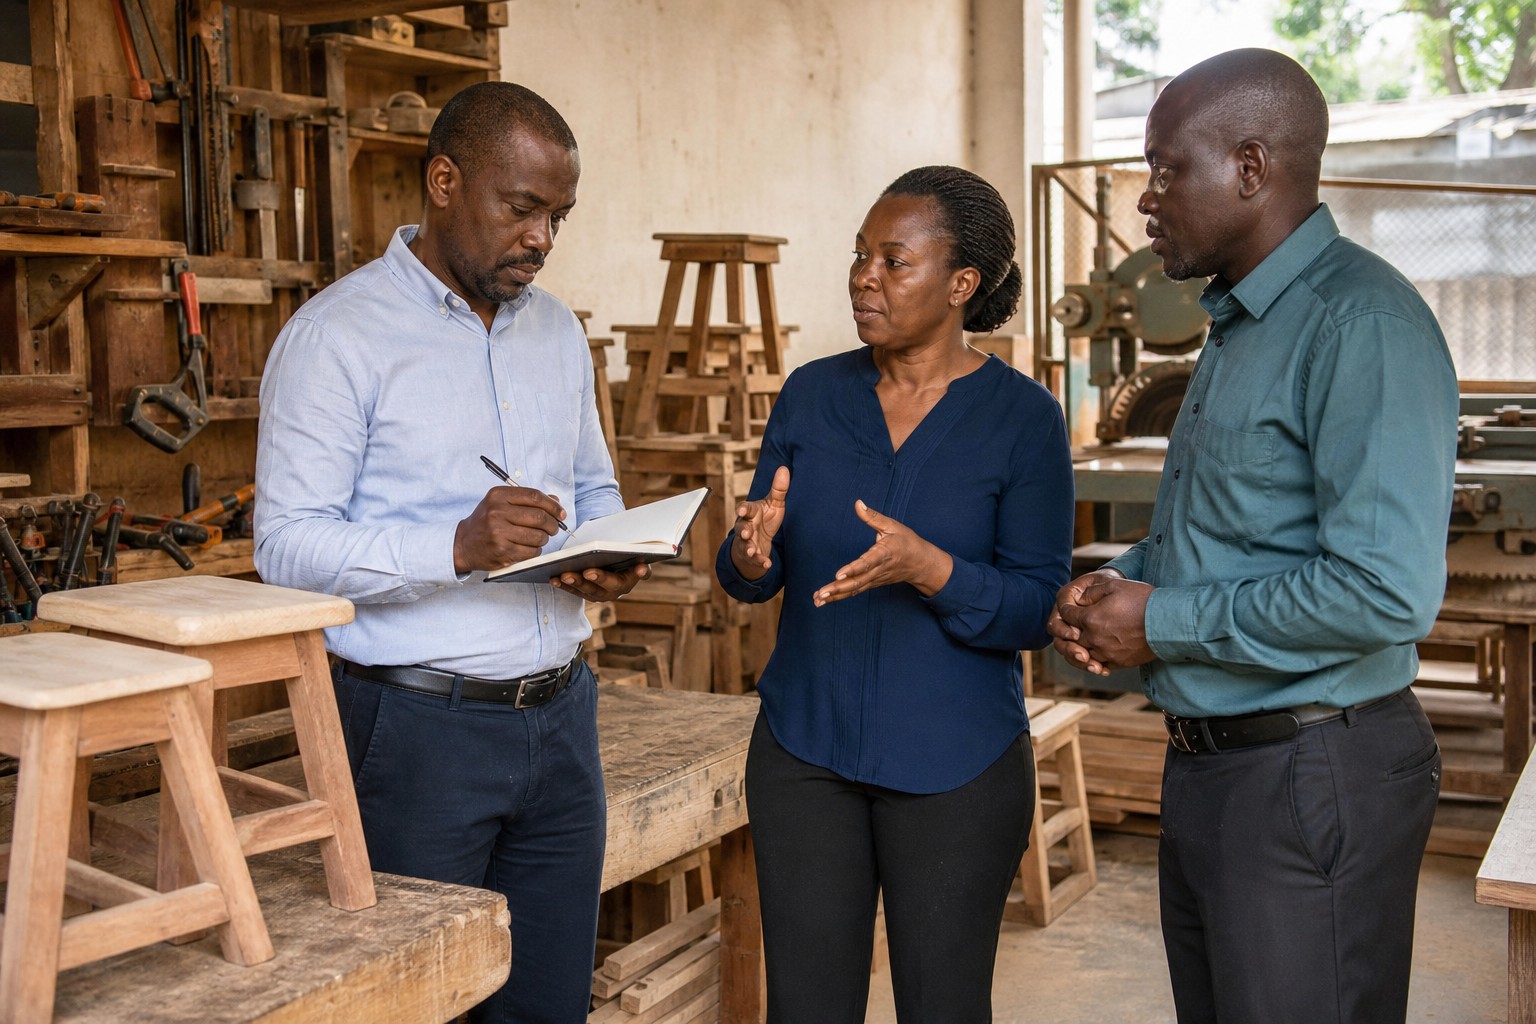
That gathering is investigative work more than form-filling. For a company it often means going to look: the premises, the machines, the stock, the way people actually work. A workshop says in ten minutes what a questionnaire never will, and that is where both the pointless cover and the gaping holes become visible.
Declaring the risk binds the client. What is declared underpins the pricing and, often, the extent of the cover. So a broker explains why playing down a piece of information at the point of taking out a policy amounts to weakening your own claim later — and never fills in a declaration on a client's behalf on points they have not checked.
Approaching several insurers, and saying so when there is only one
Once the need is described, the broker approaches companies. The number of offers actually available depends on the market, the type of risk and sometimes the location: some needs are covered by many insurers, others by a single one, others again by none on reasonable terms.
Professional honesty here means not dressing up a forced choice as a selection. Saying "only one company will take this risk" is useful information; presenting that single offer as the outcome of a comparison is a lie by staging.
Sometimes the conclusion is negative too: none of the available offers justifies the outlay given what it really covers. An intermediary able to say that keeps a client; a salesperson does not.
The written comparison: cover, exclusions, excess, limits
The trade's central deliverable is a comparison document. It sets out side by side, item by item, what each contract covers and what it does not.
Four elements matter there as much as the price. The cover, meaning the events insured and in what circumstances. The exclusions, which define the contract's real extent in negative. The excess, the share left to the insured. The limit, beyond which the insurer stops paying. To which are added the term, any waiting periods before certain cover applies, and the conditions for notifying a claim.
Insurance does not cover "everything", and a broker who lets a client believe otherwise is preparing a dispute. The cheapest option is sometimes the right one and sometimes not: it depends on what has been excluded, and no ranking replaces that sentence.
Amounts, rates, excesses and limits depend on the contract, the insurer, the market and the risk as described. No figure carries over from one file to another, and an intermediary quoting a price before studying a situation is not talking about their client's file.
Taking out the policy: what the client signs, and what they receive
Then comes the administrative stage, which deserves close attention because that is where files get lost. Assembling the documents requested, submitting them, obtaining the contractual paperwork, checking that what is written matches what was presented, and handing the whole thing to the client.
The client leaves with documents of unequal weight: the general conditions, the particular conditions specific to their situation, a certificate where one is provided for, a payment schedule where relevant. It is the particular conditions that establish what was personally taken out, and it is the document most policyholders never reread.
The broker meanwhile holds sensitive information: declared health status, the value of possessions, an address, travel habits, company data. None of it should circulate beyond what taking out the policy requires, and an identity document or a statement is not sent through an ordinary channel on the grounds that it is quicker.
The claim: supporting a notification without deciding the outcome
This is the moment an intermediary is really judged. They help notify the claim in the required form and within the time allowed, gather evidence of the damage, answer the insurer's requests, follow progress and chase.
They have no power to decide. Payment depends on the cover taken out, the exclusions, whether the notification complies, and the insurer's assessment of the circumstances. A broker promising that a claim will be met is promising something that is not theirs to give.
Still less do they take part in building a claim. Exaggerating damage, declaring an item that never existed, backdating an event or altering a document are not grey areas: they are fraud, and the professional who lends a hand loses their trade before the client loses their policy.
How a broker is paid, and why that is said out loud
An intermediary is often paid through a commission from the insurer selected, included in the premium; sometimes through fees agreed with the client; sometimes both, depending on the nature of the file. The applicable rules differ from country to country.
That way of being paid creates a tension better named than denied: if not every offer earns the intermediary the same amount, they have an interest of their own at the moment of advising. You do not resolve that tension by claiming neutrality, which nobody can prove, but by making the information available — saying how you are paid, and answering when a client asks what one offer earns compared with another.
A client may legitimately ask that at the first meeting. How the question is received often tells them more than a brochure.
The life of a contract: renewal dates, renewal, cancellation
A contract is not a single act but an ongoing relationship. Situations change: a vehicle is sold, a business grows, premises move, an employee is hired, a stay is extended. Cover that has not followed those changes can become useless without anyone noticing before a loss.
Follow-up therefore means periodically reviewing the fit, flagging what has to be declared to the insurer, preparing renewal dates and examining renewals rather than letting them roll over by default. The ways a contract may be cancelled, the notice required and the cases where it is possible belong to the contract and to the applicable law; they are checked, not assumed.
In the African context
Insurance markets differ profoundly from one African country to another, in size, regulation and history. Fourteen states of Central and West Africa share a common framework within the Inter-African Conference of Insurance Markets, which has an insurance code and a regional supervisory commission. That framework concerns its member states and nobody else: the rest of the continent falls under other national authorities, with their own rules.
Access to financial services is a second dividing line. The World Bank notes that worldwide a substantial share of the adult population still has no account, while pointing out that digital financial services lower the cost of access and at the same time create new risks for consumers. The Global Findex surveys show account ownership rising steadily and digital tools playing a growing part — a movement that does not read the same way across countries, between rural and urban areas, or across income levels.
Payment methods follow directly from that. Depending on the market, cash, bank accounts, cards and mobile wallets coexist, the growth of the latter being documented by the GSMA across several regions of the world. For a broker that changes very concrete things: how a premium is collected, what proves a payment, which payment rhythms are possible, and how a document reaches a client far away.
Then there are field realities that can be neither generalised nor ignored: long distances between a client and their insurer, several working languages, a cost of service that weighs more heavily on small policies, mistrust sometimes fed by bad experiences, and a clientele largely made up of self-employed people and small structures. A useful intermediary in that setting is first of all one who explains slowly and is willing to say no.
What an insurance broker does not promise
They do not promise a payout, nor a settlement time, nor the absence of a dispute. They do not guarantee the lowest price on the market, which no intermediary can verify exhaustively. They set no reference tariff: a premium depends on the risk described, the contract, the insurer and the market.
Nor do they stand in for neighbouring professionals. They are neither the assessor who values damage, nor the lawyer who runs litigation, nor the accountant who records premiums in a company's books, nor an investment adviser — presenting an insurance contract as a yield product is a slide out of the trade described here.
What they can commit to is precise: a situation described honestly, several insurers approached where the market allows it, a written comparison, exclusions stated out loud before signature, and someone reachable on the day a loss occurs.